 Issue #26
Making Price Tell the Truth, with Laurent Babikian
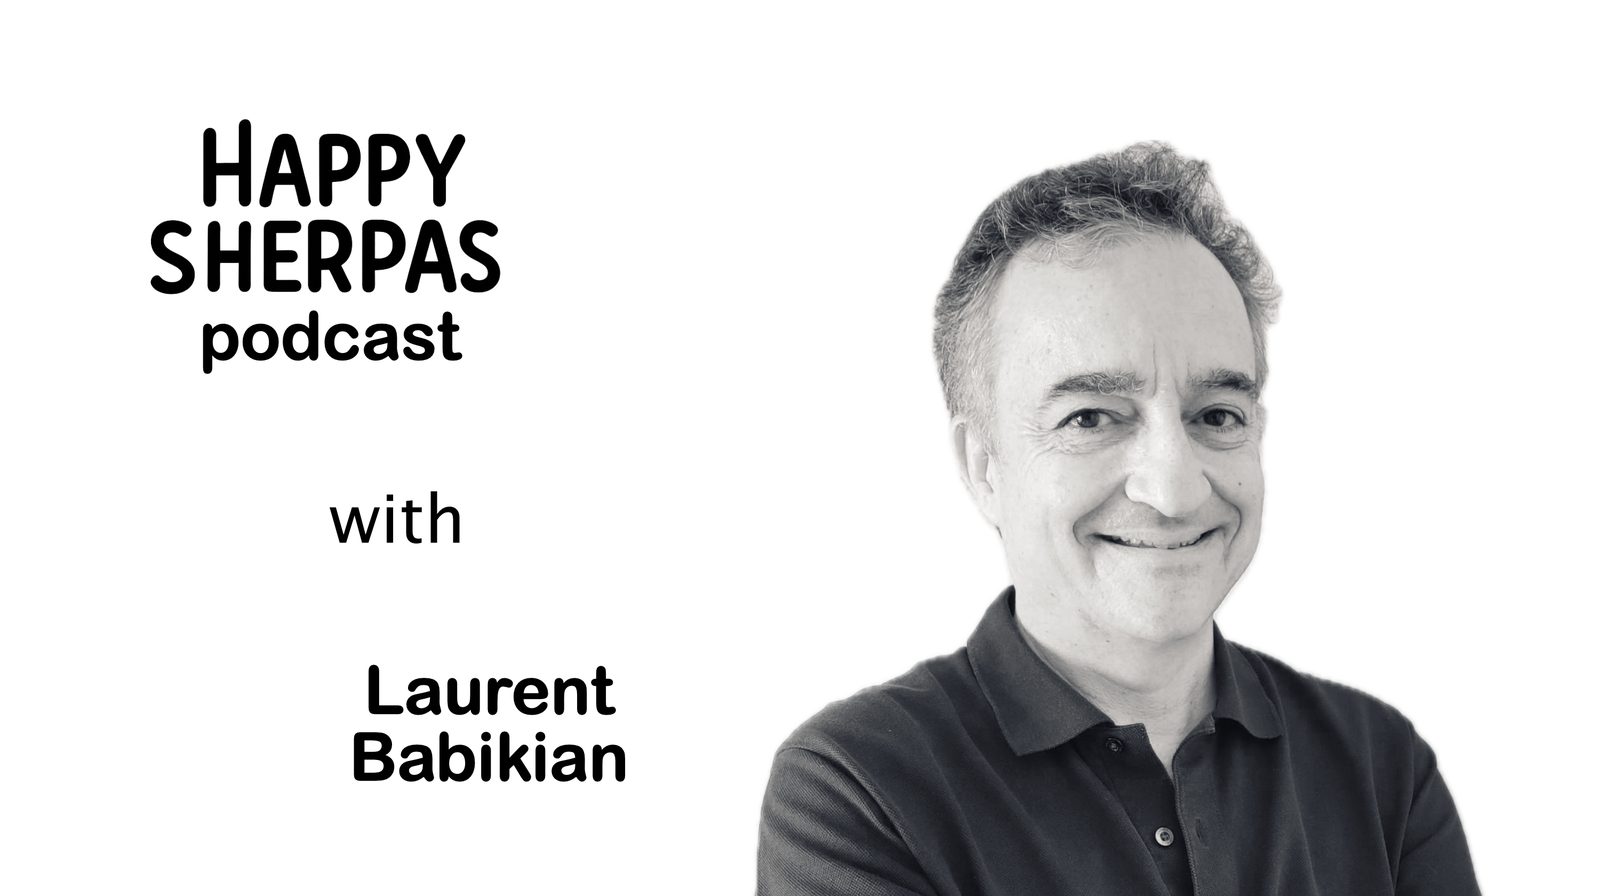
I had the pleasure of welcoming Laurent BABIKIAN on the latest episode of Happy Sherpas, the podcast I co-host with Virginie Vitiello. Laurent spent ten years selling derivatives at Crédit Agricole Indosuez before deciding, in his own words, that he was “not creating anything.” He left for Brazil where he contributed to the startup ecosystem, then spent eleven years at the Carbon Disclosure Project pushing investors toward the 1.5°C target. Today he advises executive committees on transition strategy and teaches at HEC Paris. It is reassuring, every time, to meet someone who made the same leap toward purpose and common good that I strive to make every day.
Europe’s uncomfortable arithmetic
Laurent opened with a striking number: 75 trillion dollars. That is roughly the value of Russia’s natural resources at market price. The US comes second, Iran fifth, China sixth. Europe has almost none. We import what we transform, which means we also import the volatility. And there is a larger story in the background: roughly half of world GDP in purchasing power parity now comes from Asia, with China ahead of the US. And the petrodollar arrangement that has underwritten American power since 1973, oil priced in dollars in exchange for security guarantees, is under strain. The situation in the Middle East comes to mind. But we should add that the US’s attempt to shrink its own trade deficit, through tariffs and other policies, means fewer dollars flowing out for others to hold as reserves (and thus finance the US Treasury). This “Triffin dilemma” is a tension to keep in mind when looking at the world today.
I do not read any of this as doom-mongering. I read it as a description of the ground Europe is actually standing on, which is thinner than most boardrooms admit, and which explains why Laurent spends his time trying to change the rules of value creation. He makes the point for circular economics and is in favour of materials being treated as patrimonial assets rather than depreciating ones. We already covered these points in my previous letter “#22 - Circular Programmed Sustainability with Christian Bruère.” So here, I would like to delve deeper into another of Laurent’s contributions: the generalisation of sustainability-linked pricing.
Sustainability-linked pricing
Laurent’s idea is that companies should let prices vary according to the sustainability performance of whoever they are dealing with, supplier, client, bank, or state. Take a company’s scope 3 emissions, split between what suppliers bring in and what clients do with the product once sold. If a supplier helps you cut your footprint, you pay them more, not less, because you want them to keep doing it. If a client’s use of your product increases your footprint, you charge them more too. As Laurent put it:
If my client enables me to decrease my Scope 3, I have to sell to this client at a lower price. If it does the contrary, I will sell at a higher price.
Take aluminium. The same metal could go into a bicycle frame meant to last thirty years, or into disposable coffee capsules and food trays used once and thrown away. With sustainability-linked pricing, the aluminium heading for the bike frame costs less, because that client is helping keep the seller’s footprint down for decades. The aluminium heading for the capsules and the trays costs more, because that client is buying a few minutes of use out of the same extracted metal. It is a small reversal with large consequences: price stops being only a signal of scarcity and becomes a signal of consequence.
What water has already taught us
Water is a domain where we already learned to pay for a co-benefit, setting precedents that should inspire other industries. Around Vittel and Evian, farmers have been paid since the 1990s to reduce fertiliser and pesticide use and adopt extensive grazing, in exchange for protecting the water table the brands depend on. It is a private arrangement, but a durable one.
The public version is even more telling. New York City’s water utility pays farmers in the Catskills and the Delaware watershed to farm in ways that protect the drinking water of nine million residents. The reasoning was purely financial: doing this was cheaper than the eight to ten billion dollars the city would have needed to build a filtration plant, plus a hundred million a year to run it.
France runs a smaller, newer version of the same logic through its water agencies: 654 farms are now under contract on nearly 74,000 hectares in the Seine-Normandie basin alone, backed by more than 50 million euros in funding.
None of these cases waited for a treaty or a global framework. They are all decisions made locally, one balance sheet at a time, proof that we can move on despite the sluggishness of international cooperation.
The same logic extends to floods. In Pickering, in the north of England, farmers upstream now manage soil and build small leaky dams to slow water down before it reaches the town, after a conventional concrete flood defence was judged too expensive under standard cost-benefit rules. If the flood benefit on its own is modest, the economics work once you count the habitat and carbon co-benefits alongside it.
China ran the same idea at a completely different scale after the 1998 Yangtze floods, paying farmers to convert steep cropland to forest across nearly fifteen million hectares. Estimates of the carbon this sequestered vary a lot by study, but they should run into the billions of tons of CO2 over the longer time horizon. Yes, billions!
When money itself gets priced for its impact
Laurent points to interest rates as an example of where differentiated pricing already exists: sustainability-linked loans now make up roughly 40% of the labelled loan market. Interest rates vary depending on whether the company hits its sustainability targets or not. Unfortunately, the UK’s financial regulator confirmed in 2025 that, despite real improvements in how these loans are structured, the margin adjustments tied to hitting or missing sustainability targets remain, in its own words, de minimis, too small to meaningfully change behaviour. The idea works. The scale doesn’t, yet.
I would add that this differentiated pricing could also work for central banks, setting the most important rates of our economies. The Network for Greening the Financial System published a framework in January 2026 for weighing climate factors on both sides of a central bank’s balance sheet. China’s central bank has offered a preferential 1.75% rate for green lending since 2021, and the Bank of Japan a 0% rate for climate-related financing since 2022. The European Central Bank says it is looking into it.
I believe a green risk-free rate is actually one of the main levers to use if we are to transform our economies at scale. However, nothing is implemented yet.
Conclusion
What struck me across this conversation is how familiar the pattern is at every scale, carbon, water, floods, bank loans, central bank rates... The tool almost always already exists. But it is almost always too small to matter. This is not a knowledge problem anymore. We are well past the point of needing another framework, another pilot, another proof of concept. We have the theory and we have the tools. What is missing is the will to use them at the scale the problem actually requires.
It should be a vanilla product on the market. It is not.
That is what Laurent says about sustainability-linked loans; it could apply to almost everything in this letter. So here is the question I keep turning over: if the instruments already exist, from a farmer’s field to a central bank’s balance sheet, what exactly is stopping us from using them properly?
Listen to this episode of Happy Sherpas on Apple Podcasts, Spotify or YouTube.
As usual, this letter, originally published on LinkedIn, is meant to open a discussion: join it here.
Lenny Kessler